Seller financing is a purchase where the seller acts as the lender: the buyer makes a down payment, signs a promissory note, and pays the seller directly instead of a bank. It is not exotic. Florida recorded 7,835 seller-financed transactions in 2025, the second most of any state and about 9 percent of the national total, according to the NoteInvestor seller financing industry report. For buyers who do not quite fit a conventional loan, and sellers who want income instead of a lump sum, it is one of the most useful options nobody asks about.
Why this is a Florida story
Florida is a natural home for this. Retirees selling free-and-clear homes, self-employed buyers with strong income and unconventional paperwork, and out-of-state investors moving fast all create matchups a bank cannot serve efficiently. Seller-financed notes reached roughly $29.5 billion nationwide in 2025, and the market grew about 8 percent in 2024 even as overall sales fell, with the average note balance around $271,655. It is a niche, but a growing one.
How it actually works
The structure matters. In Florida this is a normal sale with title transferring to the buyer at closing, not a contract-for-deed arrangement. The buyer signs a promissory note for the balance, and the seller takes back a purchase-money mortgage recorded in the county where the property sits. That recording secures the seller's right to payment and the buyer's right to build equity. Monthly payments go directly to the seller, often through a servicing arrangement or a title company, and the terms live in the note, not in a lender's underwriting manual.
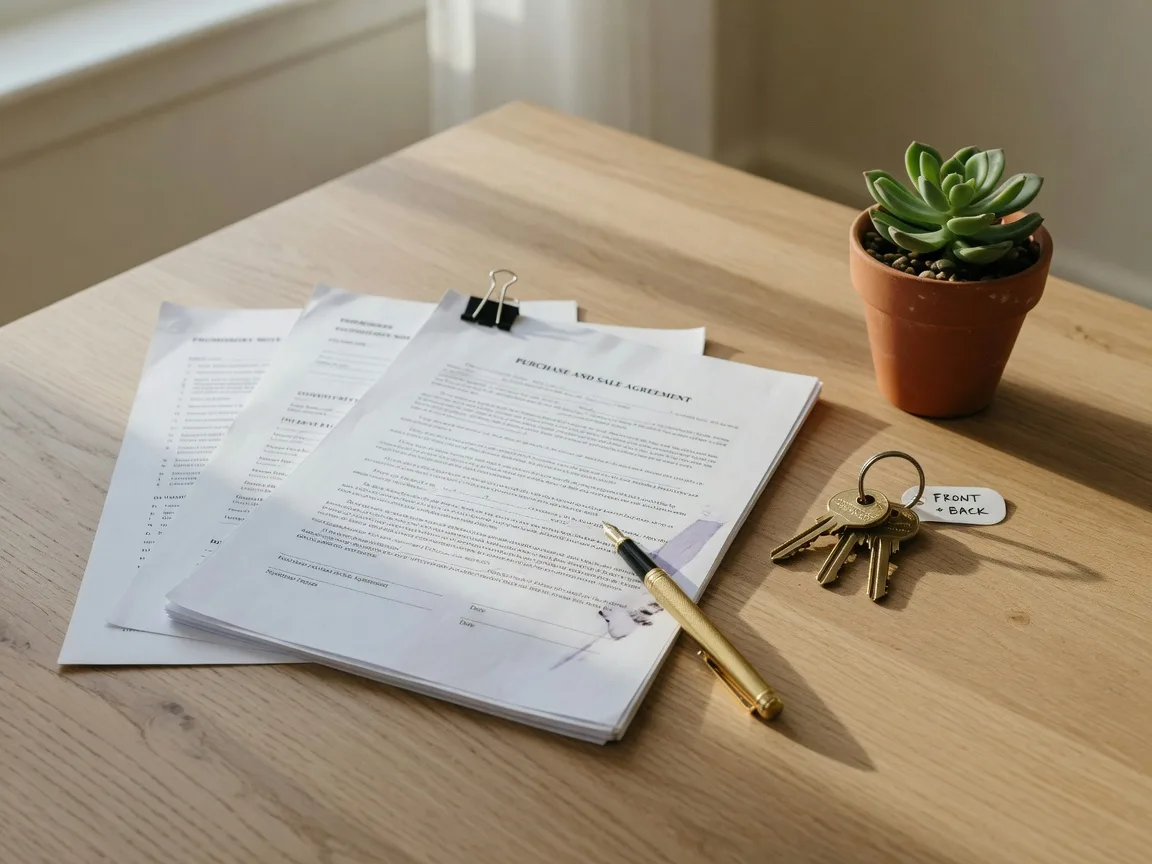
Seller financing changes the paperwork at the table: a promissory note and a recorded mortgage instead of a bank's loan file.
The typical terms
Terms are negotiated, not dictated by an underwriter. Down payments commonly run 10 to 20 percent, with many sellers asking near the top of that range. Rates typically land 1 to 2 points above what banks charge, often in the 6 to 10 percent range, because the seller carries the credit risk. Many notes amortize over 20 or 30 years but carry a balloon payment due in 3 to 10 years, commonly around 5, when the buyer refinances into a conventional loan.
The Florida costs most buyers miss
Florida has its own costs here. The documentary stamp tax runs 35 cents per $100 of the amount financed on the note, and the nonrecurring intangible tax adds 20 cents per $100 on the recorded mortgage, per Florida Department of Revenue rules. Attorney and title fees apply on top, and who pays is negotiated. Seller financing usually costs less than a conventional closing, but it is not free, and the numbers deserve a line-by-line look before you sign.
The honest risks
The balloon is the biggest one. If you cannot refinance when it comes due, you could lose the home, so the refinance plan matters as much as the monthly payment. Ask whether the seller has an existing mortgage: most residential loans carry a due-on-sale clause, so a seller who keeps a loan usually must pay it off at closing, or the lender can call the balance due. Florida caps interest at 18 percent simple on loans under $500,000 and 25 percent above that, well above what most sellers quote. And because a seller acting as lender is not a regulated bank, documentation quality varies; for owner-occupied buyers, federal rules restrict balloon payments in certain seller-financed deals. The structure has to be set up properly from day one, which is why the right team matters.
When it makes sense
Seller financing shines for buyers who are creditworthy but do not fit a bank box: recent self-employment, a first-time buyer with strong income and a thin credit file, or an investor who needs to move fast. It helps sellers who want a wider buyer pool, steady income, or a quicker close without a lender's appraisal timeline. It is not for everyone, and it rewards the same homework as any purchase: title work, attorney review, insurance numbers, and an honest conversation about what happens when the balloon comes due.
Understanding seller financing is exactly the kind of option people miss when they assume the only path is a conventional loan. If you are selling, it fits the options you have before you list, and if your gap is buying before your current home sells, the bridge and equity routes are covered separately. Bring the idea up early: structuring it right changes the price, the closing, and the note itself.
If a seller offered you seller financing at a slightly higher rate but a faster, simpler close, would you take it?
Or would you rather hold out for a conventional loan and the protections that come with it? Tell me your reasoning. The trade-off is different for every buyer, and your answer actually shapes how I would structure the deal.
Roger Reed
Realtor, RAR Property Group | eXp Realty
I help buyers, sellers, and investors throughout Florida's Gulf Coast make smarter real estate decisions, including creative financing structures like seller-held notes. Licensed in Florida: SL 3407667.
Get in touchWant to know whether seller financing fits your purchase or your sale?
Send me a message or grab a quick call. I will walk you through the structure, the Florida costs, and the risks before you commit to anything.
Roger Reed · 941-402-0083 · roger@rarpropertygroup.com